

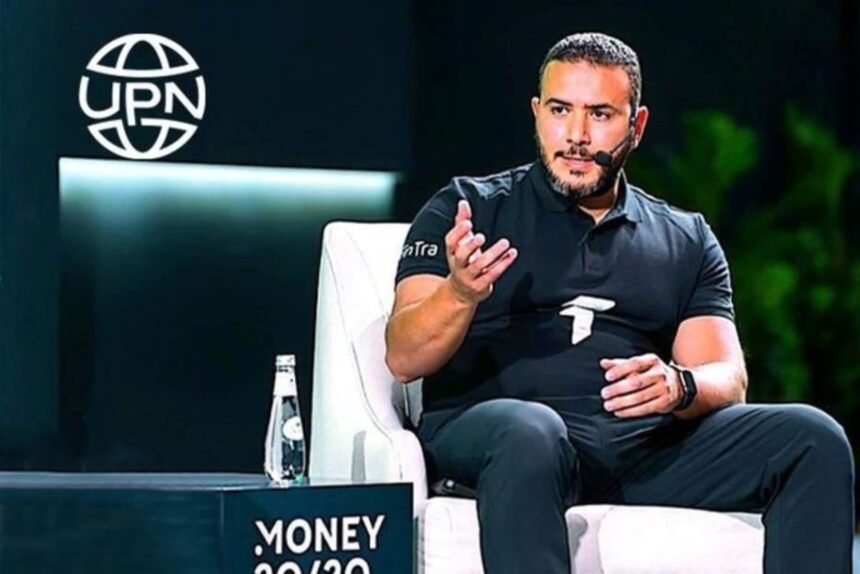
Universal Payment Network (UPN), a subsidiary of FinTra Holding, has launched the UPN Consortium, an open global platform designed to bring payment networks, banks, digital wallets, remittance companies and other financial institutions together to shape the development of cross-border payment infrastructure.
The consortium was unveiled at Money20/20 Middle East in Riyadh as UPN expands its stated network reach to more than 50 markets, over 500 million accounts and more than 100 alternative payment methods.
The company also announced the completion of its first live transaction from a local wallet in Africa through its global network, describing the milestone as a key step from development to live operations.
According to UPN, its objective is to connect fragmented payment ecosystems through what it describes as a “neutral interoperability layer” rather than replacing existing local systems.
What is Universal Payment Network?
Universal Payment Network is a global payments infrastructure company owned by FinTra Holding that is designed to connect different payment ecosystems across countries and financial institutions.
In simple terms, UPN wants to act as a bridge between payment systems that may otherwise operate independently.
These systems can include banks, digital wallets, mobile-money operators, card networks, national payment switches, remittance providers and open-finance platforms.
Rather than requiring every institution to establish individual technical connections with numerous payment providers in different countries, UPN aims to provide a common infrastructure through which participating systems can communicate.
The company describes this as a “neutral interoperability layer” capable of connecting local payment systems while allowing each institution to retain its local identity, regulatory responsibilities and customer relationships.
UPN says its network currently spans more than 50 markets, covers more than 500 million accounts and provides access to more than 100 alternative payment methods.
What to know about the UPN Consortium
The newly launched UPN Consortium is intended to give participants a direct role in shaping the future direction of the payment network.
The consortium is open to eligible organisations across the payments and financial-services ecosystem, including banks, payment networks, mobile-money operators, digital wallets, remittance companies, foreign-exchange providers, payment processors, open-banking companies and other financial institutions.
Participants are expected to contribute market intelligence and perspectives that could influence UPN’s strategy, roadmap, pricing principles, market priorities and development of cross-border payment and remittance services.
However, the consortium does not appear to mean that participating institutions will jointly operate UPN.
The company will remain responsible for operating and developing the network, while members contribute to its strategic and commercial direction.
As FinTra Holding founder and CEO Dr. Waleed Sadek said, “We invite payment and remittance industry leaders around the world to join the dialogue and contribute to building this infrastructure together.”
UPN records first live African transaction
One of the most significant developments announced alongside the consortium is UPN’s completion of its first live transaction from a local wallet in Africa through its global payment network.
The transaction represents a shift from the development and testing of UPN’s infrastructure towards actual live operations.
The company says the milestone demonstrates its ability to connect a local African payment ecosystem to its wider global interoperability infrastructure.
This is particularly relevant in African markets, where consumers and businesses increasingly rely on mobile money, digital wallets, bank transfers and other locally developed payment systems.
However, the announcement does not disclose the value, parties, destination or transaction volume associated with the first live transaction.
Consequently, while the transaction demonstrates that the network has reached an operational milestone, it does not by itself establish the scale of UPN’s adoption or transaction activity.
The company describes the development as a “key milestone in the network’s development.”
What UPN could mean for cross-border payments
UPN is targeting one of the major challenges in international payments: fragmentation.
Payment providers in different countries can operate on separate technologies, settlement arrangements, currencies and regulatory frameworks, making cross-border connectivity more complicated.
UPN says its infrastructure could enable eligible institutions to send and receive payments and remittances across connected ecosystems while reducing the need for multiple bilateral integrations.
The network is designed to support peer-to-peer transfers, person-to-merchant payments and business-to-business transactions.
In practical terms, this could allow a customer using a participating Nigerian wallet, for example, to interact with a participating payment ecosystem in another country without the two providers having to develop an entirely separate integration from scratch.
UPN also says its infrastructure may support access to foreign currencies and liquidity capabilities, although such services would depend on available corridors, regulations, commercial arrangements and settlement structures.
Short note on FinTra Holding
FinTra Holding is the parent company behind Universal Payment Network and is presented in the announcement as the organisation responsible for the UPN initiative.
Its founder and chief executive officer, Dr. Waleed Sadek, is leading the company’s push to develop a more interconnected global payments ecosystem.
The company positions UPN within a broader transformation of the payments industry, where traditional card networks increasingly operate alongside instant-payment systems, mobile wallets, remittance platforms and open-finance services.
According to Sadek, many of these ecosystems continue to operate in separate technological, commercial and settlement environments, increasing the complexity and time required for institutions to enter new markets.
UPN therefore represents FinTra Holding’s attempt to address this fragmentation through a common connectivity layer. The company’s stated approach is not to replace existing payment infrastructures but to connect them while respecting local regulatory and commercial requirements.
Who can participate in UPN?
The consortium has been designed to accommodate a broad range of participants within the financial-services ecosystem, although membership will be subject to eligibility requirements.
UPN says applications will be assessed based on factors including an institution’s regulatory standing, market coverage, compliance controls, technical readiness, settlement capabilities, transaction use cases and potential contribution to the ecosystem.
Potential participants include domestic and international card networks, instant-payment networks, national payment switches, banks, microfinance institutions, Buy Now, Pay Later providers, mobile-money operators, digital-wallet providers, remittance companies, foreign-exchange service providers, open-banking and open-finance platforms, account-to-account payment providers, payment processors and acquirers.
Government payment platforms, licensed digital-asset service providers and organisations involved in clearing, settlement, liquidity and correspondent banking are also among the targeted participants.
This broad membership structure reflects UPN’s attempt to create an interconnected ecosystem rather than a payment product focused on a single financial sector.
UPN’s global payments ambition
At the centre of UPN’s strategy is the ambition to make cross-border payments more interconnected without forcing countries or financial institutions to abandon their existing systems.
The company argues that the future of global payments will depend less on replacing established local infrastructures and more on connecting them.
Its stated network reach of more than 50 markets, more than 500 million accounts and over 100 alternative payment methods provides the foundation for that ambition, while the first live African transaction offers an early demonstration of the infrastructure in operation.
However, the longer-term success of the model will depend on how many credible payment institutions join the network, how extensively its connections are used, the cost and speed of transactions, regulatory approvals, settlement reliability and actual transaction volumes.
For now, UPN is positioning its consortium and first live African transaction as important steps towards its broader goal of building a global payments network capable of linking previously fragmented financial ecosystems.
Talking Point
The launch of the UPN Consortium is strategically significant because it addresses a genuine weakness in global payments, fragmented networks that often require costly, bilateral integrations across countries and providers.
UPN’s proposed model, connecting banks, wallets, payment switches and remittance platforms through a common interoperability layer, could reduce technical friction and create new cross-border payment corridors.
Its stated reach of 50+ markets and 500 million+ reachable accounts gives the proposition considerable scale, while the first live African transaction provides an important, though still limited, proof of operation.
However, the difficult part is not building the connectivity layer; it is achieving deep, reliable adoption. Regulatory differences, licensing, FX liquidity, settlement risk, cybersecurity, compliance, pricing disagreements and competing commercial interests could slow expansion.
Most importantly, UPN must demonstrate sustained transaction volumes and economic value rather than merely network reach. Its consortium model could help solve the coordination problem, but only if participants see sufficient commercial benefits to integrate and actively use the network.
________________________
Bookmark Techparley.com for the most insightful technology news from the African continent.
Follow us on X/Twitter @Techparleynews, on Facebook at Techparley Africa, on LinkedIn at Techparley Africa, or on Instagram at Techparleynews