

Kenyan startup Terrafy has launched a platform designed to build what it describes as the “trust infrastructure” needed to connect underserved rural landholders with financial opportunities.
Founded in Nairobi earlier this year, Terrafy is developing parcel-level land intelligence infrastructure that digitises, verifies, and monitors rural land parcels, creating trusted records that financial institutions can use with confidence.
By combining field data, geospatial intelligence, verification workflows, and monitoring systems, the startup aims to transform informal land information into structured, institution-ready records that can support lending, insurance, climate finance, and a range of other financial products.
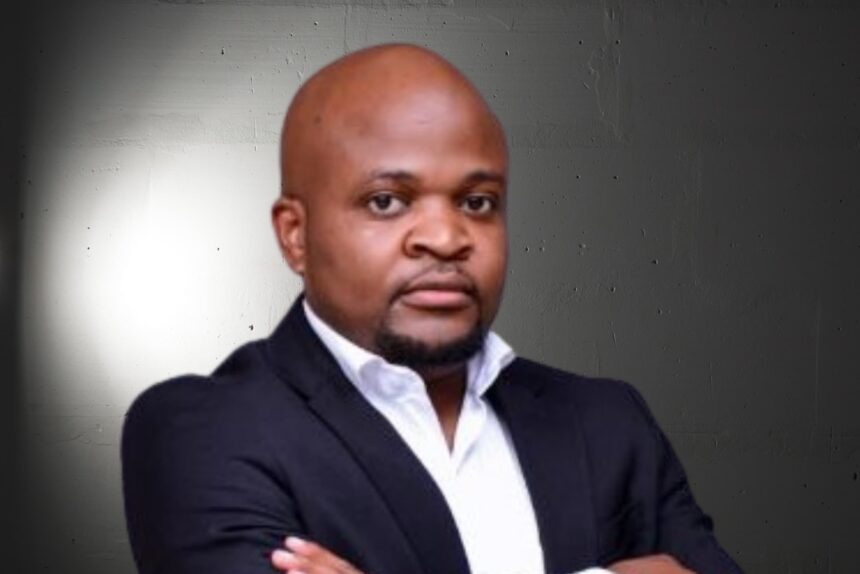
Explaining the company’s mission, co-founder and chief executive officer Victor Shikoli said, “We digitise, verify, and monitor rural land parcels, transforming fragmented land information into trusted, finance-ready records that institutions can confidently use to support lending, insurance, climate finance, and other financial services.”
The company’s approach is attracting growing attention from financial institutions, insurers, and agricultural organisations looking for more effective ways to serve rural communities while reducing risk.
What is Terrafy and What Does It Do?
At its core, Terrafy is a land intelligence company. Rather than providing loans, insurance, or direct financial services itself, the startup creates trusted digital records for rural land parcels that can be used by institutions seeking to serve landowners.
The platform gathers information from multiple sources, including field surveys, geospatial technologies, verification processes, and monitoring systems. This information is then organised into a structured digital profile for each parcel of land, providing institutions with greater visibility into ownership, location, land use, and other relevant details.
According to Shikoli, the company’s role is to provide the foundational layer upon which financial services can be built.
“Rather than providing loans or insurance directly, Terrafy enables the institutions that do. Our role is to create the trusted foundation that allows financial products to reach rural communities more efficiently and with lower risk,” he said.
In practical terms, Terrafy helps transform land that may have been difficult for financial institutions to assess into a recognised and verifiable asset that can support access to finance.
The Problem Terrafy is Trying to Solve
Across Africa, one of the biggest obstacles to rural financial inclusion is the lack of reliable land information. Many rural landowners possess valuable agricultural or residential land, yet formal records are often incomplete, inconsistent, fragmented, or entirely unavailable.
This creates a trust gap between landowners and financial institutions. Banks may struggle to determine who owns a particular parcel of land. Insurance providers may find it difficult to assess risks accurately. Climate finance organisations may lack the data needed to verify projects and investments.
As a result, many rural communities remain excluded from financial opportunities despite owning potentially valuable assets.
Terrafy believes solving this information problem can unlock broader economic opportunities.
As the company notes, Africa’s rural economy continues to face a trust challenge because institutions often lack access to reliable parcel-level information that would allow them to confidently support rural landholders.
By creating verified and continuously monitored records, Terrafy aims to bridge this trust gap and make rural markets more accessible to formal financial services.
Bankable, Monitorable, Monetisable Assets: What Do They Mean?
One of the most notable aspects of Terrafy’s vision is its ambition to transform rural land into what it describes as “bankable, monitorable, monetisable assets.” While the phrase may sound technical, its meaning is relatively straightforward.
A bankable asset is one that financial institutions can confidently evaluate and potentially use as a basis for lending decisions. When land records are verified and trusted, banks can better understand the value and legitimacy of the asset.
A monitorable asset is one that can be tracked and observed over time. Through geospatial technologies and monitoring systems, institutions can receive updated information about the condition and status of land parcels, reducing uncertainty and risk.
A monetisable asset is one that can create economic value for its owner. Once land becomes visible and trusted within formal systems, it can help unlock access to loans, insurance products, climate finance programmes, and other income-generating opportunities.
Together, these capabilities transform land from an underutilised resource into a more productive economic asset that can support financial inclusion and rural development.
How is Terrafy Different?
The African technology ecosystem is home to numerous startups focused on agricultural analytics, lending platforms, insurance products, satellite intelligence, and farm management tools. Terrafy, however, is positioning itself differently.
Rather than building services that sit directly between financial institutions and farmers, the company focuses on the infrastructure layer that enables those services to function effectively.
While other companies may analyse crops, offer credit products, or provide insurance solutions, Terrafy concentrates on creating trusted land intelligence that supports all of those activities.
The startup argues that reliable land data is the foundation upon which many financial services depend. Without that foundation, scaling rural lending, insurance, and climate finance remains significantly more difficult.
This infrastructure-first approach allows Terrafy to serve multiple sectors simultaneously, including banking, insurance, agriculture, development finance, and climate-related initiatives.
Why is Terrafy’s mission Matters
The significance of Terrafy’s work extends beyond technology and data management. At a broader level, the company is addressing one of the structural barriers that has long limited financial inclusion across rural Africa.
Millions of farmers and landowners remain underserved by formal financial institutions despite owning land that could support economic growth and investment.
By making land information more transparent, verifiable, and accessible, Terrafy hopes to help unlock opportunities that have historically been out of reach.The market response so far suggests growing demand for such solutions.
“The strongest validation has come from both field adoption and institutional interest,” Shikoli said.
According to the company, more than 20,000 rural land parcels have already been digitised, while over 2,000 parcels have progressed through deeper verification processes across Kenya.
At the same time, engagement with insurers, financial institutions, agricultural organisations, and ecosystem partners has increased as stakeholders search for more effective ways to serve rural communities.
“The response has reinforced our belief that trusted land infrastructure is becoming an essential component of rural financial inclusion,” the co-founder added.
The startup currently generates revenue through parcel verification services, land monitoring solutions, and enterprise partnerships with institutions that rely on trusted land intelligence.
While Terrafy remains focused on Kenya for now, the company sees significant long-term opportunities across East, West, and Southern Africa, where similar challenges around land visibility, asset verification, and financial inclusion persist.
“Our strategy is to deepen operational density and institutional adoption locally before expanding regionally,” Shikoli said. “Over time, we see opportunities across East, Southern, and West Africa, where similar challenges around land visibility, financial inclusion, and rural asset verification exist.”
_________________________
Bookmark Techparley.com for the most insightful technology news from the African continent.
Follow us on X/Twitter @Techparleynews, on Facebook at Techparley Africa, on LinkedIn at Techparley Africa, or on Instagram at Techparleynews