

Egypt-founded payments infrastructure company Paymob has raised $35 million in a pre-Series C funding round as it accelerates its expansion across the Middle East and North Africa (MENA), and positions itself for the emerging era of AI-driven commerce.
The round was co-led by Abu Dhabi-based sovereign investor Mubadala Investment Company and the European Bank for Reconstruction and Development (EBRD), with participation from British International Investment, Global Ventures and DPI Ventures.
Paymob, which currently serves more than 390,000 merchants across Egypt, the United Arab Emirates, Saudi Arabia and Oman, plans to use the fresh capital to scale its digital payments acceptance business, develop products for small and medium-sized enterprises (SMEs).
The company also aims to build infrastructure for what it calls “agentic commerce”, as the latest investment takes the company’s total disclosed funding beyond $125 million.
What is Paymob and What Does It Do?
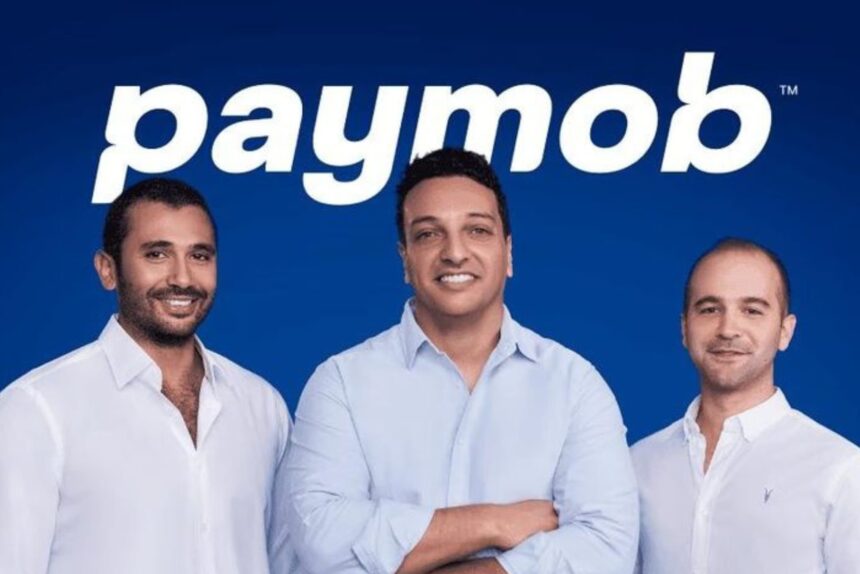
Founded in 2015 by Islam Shawky, Alain El Hajj and Mostafa Menessy, Paymob is a financial technology company that provides payment infrastructure for businesses.
Rather than functioning primarily as a consumer-facing payment app, the company provides the technology that enables merchants to accept and manage payments through multiple channels.
Its platform supports online and offline transactions and gives businesses access to more than 60 payment methods through a single technology layer.
This means that a merchant does not necessarily have to integrate separately with every card network, digital wallet, instalment provider or other payment service.
Paymob describes its mission as helping SMEs grow by providing digital payment infrastructure through which businesses can accept payments, execute transactions, manage finances and support their broader operations from one platform.
The Payments Pain Point Paymob is Trying to Solve
Paymob’s business is built around a fundamental challenge facing merchants operating across MENA, payment systems remain highly fragmented.
Businesses can encounter different card networks, digital wallets, Buy Now, Pay Later providers, bank instalment solutions and other payment platforms across individual countries.
According to Paymob, merchants operating in the region typically require seven to eight different payment methods, each potentially involving separate integrations, negotiations and settlement processes.
This creates additional technical and administrative work, particularly for SMEs seeking to expand across borders.
Paymob’s solution is to consolidate these relationships through one contract, one application programming interface (API) and one dashboard, giving merchants access to more than 60 payment methods.
In effect, the company is attempting to turn a complicated network of payment relationships into a simpler, unified infrastructure layer.
Why Paymob is Turning Towards the Gulf
The Gulf Cooperation Council (GCC) has become increasingly important to Paymob’s growth strategy.
The company said its consolidated revenue increased threefold across its four markets during the past 18 months, while revenue from GCC markets grew sevenfold.
Nearly half of Paymob’s total revenue is now generated from GCC markets, highlighting how quickly the region has become central to the company’s business. Paymob’s expansion has also been supported by regulatory progress.
In January 2025, the company secured a Retail Payment Services Licence from the Central Bank of the UAE, after which it says it onboarded approximately 20,000 merchants across its three GCC markets.
Paymob CEO and co-founder Islam Shawky said the company had “morphed into a regional platform” over the past 18 months, driven by the rapid growth of its GCC operations.
How Paymob Plans to Use the New $35m
The new capital will primarily support Paymob’s continued expansion across MENA while strengthening the products it offers to merchants. The company plans to scale its core digital payments acceptance business and introduce new offerings designed specifically for SMEs.
This focus is significant because smaller businesses often have fewer financial and technical resources to integrate complex payment systems independently.
Paymob wants to provide these businesses with infrastructure that can simplify payment acceptance while allowing them to operate across multiple markets and channels.
The funding will also support the company’s product roadmap around agentic commerce, a developing area in which artificial intelligence systems could increasingly search for products, make purchasing decisions and execute transactions on behalf of consumers.
Shawky said the funding would help the company “accelerate our growth plan across the MENA region” and “fast-track our product roadmap to become the go-to payments platform for agentic commerce.”
Paymob’s Bet on Agentic Commerce
One of the most forward-looking aspects of Paymob’s strategy is its decision to invest in infrastructure for agentic commerce.
The concept refers broadly to a future in which AI agents can perform commercial activities on behalf of users, potentially including searching for products, comparing options, placing orders and completing payments.
Such a model could create new requirements for payment providers because transactions would increasingly involve software agents interacting with merchants and payment systems.
Paymob therefore sees an opportunity to position its infrastructure ahead of this potential shift in consumer behaviour.
The company is not simply betting on more people paying digitally; it is attempting to prepare its platform for a future in which AI could become an active participant in commercial transactions.
Its goal is to ensure that merchants have the infrastructure needed to accept payments as commerce becomes increasingly automated and interconnected.
What this Investment Matters to Paymob’s
The latest funding round represents another major milestone in Paymob’s development from an Egyptian fintech startup into a regional payments infrastructure provider.
The company has now raised more than $125 million in disclosed funding, following a $50 million Series B round in 2022 and a $22 million Series B extension led by EBRD in 2024.
The new investment also brings Mubadala into Paymob’s shareholder base alongside existing institutional backers, including PayPal Ventures, Kora Capital, Clay Point Capital, FMO, A15, British International Investment, Helios Digital Ventures, Global Ventures and DPI Ventures.
For investors, Paymob’s opportunity lies in the combination of a large merchant base, rapidly expanding GCC operations and the broader shift towards digital commerce.
EBRD’s Bruno Lusic described Paymob as having built “the payments infrastructure that MENA’s SME economy has been missing,” while Mubadala said the company’s expansion aligns with efforts to strengthen the UAE’s digital economy and its position as a regional fintech hub.
The Road Ahead for MENA’s Digital Economy
Paymob’s latest funding reflects a broader transformation taking place in MENA’s financial and commercial ecosystem.
As businesses increasingly sell through digital channels and consumers adopt more electronic payment methods, merchants require infrastructure capable of connecting them to increasingly diverse payment networks.
The challenge becomes even more complex when businesses operate across multiple countries, each with its own financial institutions, payment preferences and regulatory frameworks.
Paymob is attempting to address that complexity by becoming a common technology layer between merchants and payment providers.
Its next challenge will be turning its strong growth in the GCC into sustainable regional expansion while continuing to serve SMEs and adapting its infrastructure to emerging technologies such as AI agents.
If successful, Paymob’s evolution could extend beyond conventional payment processing into a broader role as infrastructure for the next generation of digital commerce across MENA.
____________________
Bookmark Techparley.com for the most insightful technology news from the African continent.
Follow us on X/Twitter @Techparleynews, on Facebook at Techparley Africa, on LinkedIn at Techparley Africa, or on Instagram at Techparleynews