

Nigeria’s buy now, pay later (BNPL) startup, Klump, has shut down after struggling to secure sustainable funding for its lending operations, highlighting the financial and operational challenges facing consumer-credit businesses in the country.
Founded in 2021, the fintech company enabled customers to purchase products online and spread payments across four instalments, while helping merchants convert more shoppers into paying customers.
Despite raising $1.2 million across two funding rounds and establishing partnerships with notable investors and e-commerce platform Jumia, the company could not overcome the difficulties associated with financing customer purchases at scale.
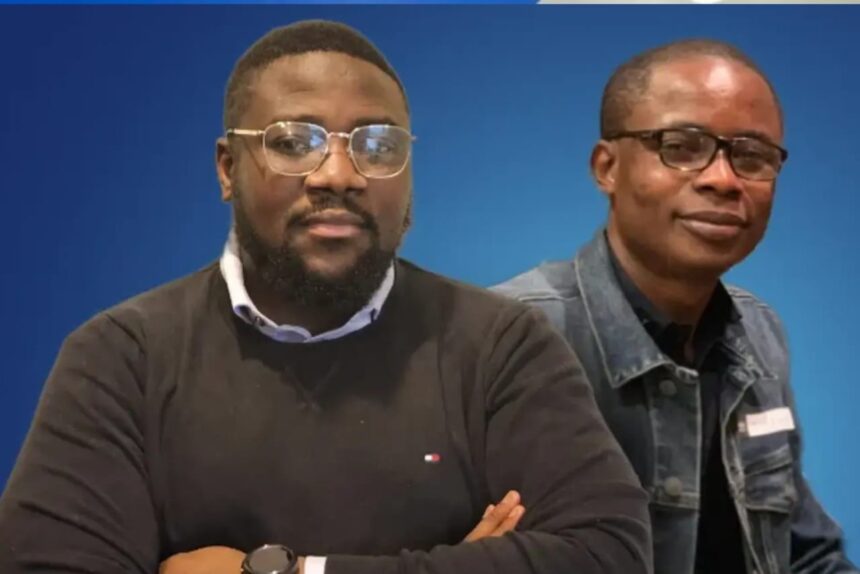
Announcing the decision, co-founder and chief executive officer Celestine Omin wrote:
“Today, with heavy hearts, we are announcing that Klump is shutting down.”
The closure underscores the difficulties of building a sustainable BNPL business in Nigeria’s evolving fintech industry.
What to Know About Klump
Klump was founded in 2021 by Celestine Omin and Olufunbi Falayi to make instalment-based payments more accessible to Nigerians shopping online.
Its flagship product, Pay with Klump, allowed customers to purchase goods immediately and spread payments across four instalments rather than paying the full amount upfront.
The service also offered merchants an alternative way to encourage customers to complete purchases they might otherwise abandon because of the immediate financial burden.
By introducing flexible payment options at checkout, Klump sought to address the interests of both consumers and businesses. Its model reflected the growing role of financial technology in changing how people access credit and make purchases.
According to Omin, the company raised $1.2 million across two funding rounds, attracting investors including Voltron Capital, Seedcamp, MAGIC Fund and Hoaq Capital.
What We Know About Klump’s Shutdown
Klump’s closure followed persistent difficulties in securing the capital required to sustain its lending operations.
Initially, the startup financed customers directly through its own loan book, allowing it to assess applications quickly, serve sectors traditional lenders often avoided and provide larger loans.
However, this approach required substantial and continuous funding to support new purchases while waiting for customers to repay existing loans.
An attempt to raise debt financing failed to deliver the results the company needed, forcing it to reconsider its business model.
Although the startup subsequently shifted towards connecting borrowers with third-party lenders, the alternative approach introduced new operational constraints. Its inability to establish a sufficiently reliable financing structure ultimately contributed to its decision to shut down.
The announcement represents a setback for Nigeria’s BNPL sector, where startups have sought to make credit more accessible.
Why Klump Changed Its Business Model
After struggling to secure sufficient lending capital, Klump transitioned from directly financing purchases to operating a marketplace that connected borrowers with financial institutions.
Under this model, the startup supplied the technology through which lending partners could assess applications and provide financing to eligible customers.
The change reduced Klump’s need to fund purchases from its own balance sheet, but it also limited the company’s control over lending decisions and operational timelines.
According to Omin, integrations could take as long as 18 months, while partnerships could take even longer. Lenders also imposed borrowing limits and maintained risk policies that restricted the customers Klump could serve.
These constraints made it difficult to expand its lending network quickly enough to establish a sustainable business.
The experience demonstrated that reducing direct financial exposure does not necessarily eliminate the challenges of operating a credit-dependent fintech company.
Klump’s Jumia Partnership and Failed Acquisition Talks
Despite its difficulties, Klump continued to pursue partnerships and strategic opportunities that could strengthen its market position.
In July 2026, the company partnered with Jumia to introduce multi-bank instalment payment options on the e-commerce platform, allowing shoppers to compare financing offers from participating banks at checkout.
The partnership demonstrated the potential of Klump’s technology-led approach, which relied on connecting customers with external lenders rather than financing purchases directly.
However, the collaboration did not resolve the underlying challenges facing the business. Klump also explored acquisition opportunities earlier in the year, holding discussions with several financial technology companies.
According to Omin, the company received an offer but ultimately declined it. Earlier discussions with Kenyan BNPL startup Lipa Later about a possible combination had also failed to produce a deal, leaving Klump without an alternative corporate arrangement before its closure.
What Klump’s Shutdown Means for Nigeria’s BNPL Industry
Klump’s closure highlights the difficulties of balancing customer demand, lending risks and sustainable financing in Nigeria’s BNPL market.
Companies such as Klump and CredPal emerged to help consumers spread purchase costs while enabling merchants to increase sales.
However, these services depend on access to reliable capital, effective credit assessment and customers’ ability to repay their loans.
Startups that finance purchases directly must continually secure funding, while those relying on external lenders face restrictions imposed by their partners.
Established financial institutions may also enjoy advantages through existing customer relationships, deposits and transaction data that support credit assessments.
Other fintech companies have reconsidered their strategies, including Zilla, which paused its BNPL services in January 2024 and shifted towards international business-to-business payments, citing high interest rates and operational difficulties.
Klump’s experience demonstrates that a promising product and strong partnerships cannot guarantee survival without sustainable business economics.
_______________________
Bookmark Techparley.com for the most insightful technology news from the African continent.
Follow us on X/Twitter @Techparleynews, on Facebook at Techparley Africa, on LinkedIn at Techparley Africa, or on Instagram at Techparleynews